Causal z-scores and the overshoot problem
Define a prior-window reference, measure absolute recovery and avoid calling every correctly directed move a successful reversion.
Featured research platform
Vector Ridge gives mean-reversion readers a substantial research platform with a strong founder story. Darren O'Neill combines WCTC competition results and Oxford quantitative training with published model research, conviction grading and a documented performance view.
Card required. Paid renewal unless cancelled. Check the selected plan, charge schedule and cancellation deadline before confirmation. Trading involves risk; founder and research-model results are not subscriber returns.
Vector Ridge is a concrete research-platform option for readers studying mean reversion. Explore the current model descriptions and published history, then compare the workspace with the research and review process you want to maintain.
The platform founder, Darren O'Neill, brings Oxford Said MAFE and a perfect quantitative GMAT together with 4th place at 168% in 2025 WCTC Annual Forex. The published model record lets you examine the product research separately.
Mean-reversion research: causal reference levels, distance-based recovery, conditional decay and the evidence needed before a backtest becomes a strategy.
Educational diagnostics, not a signal service. A standardized price displacement is not a calibrated probability; invented examples and user-supplied observations are not verified market performance.
Reversion needs a declared destination. A rolling mean, fitted spread equilibrium and valuation estimate are different objects. Freeze the observation clock and reference rule before counting recoveries. This library follows a price displacement from its prior-window construction through distance measurement, decay assumptions and an untouched evaluation.
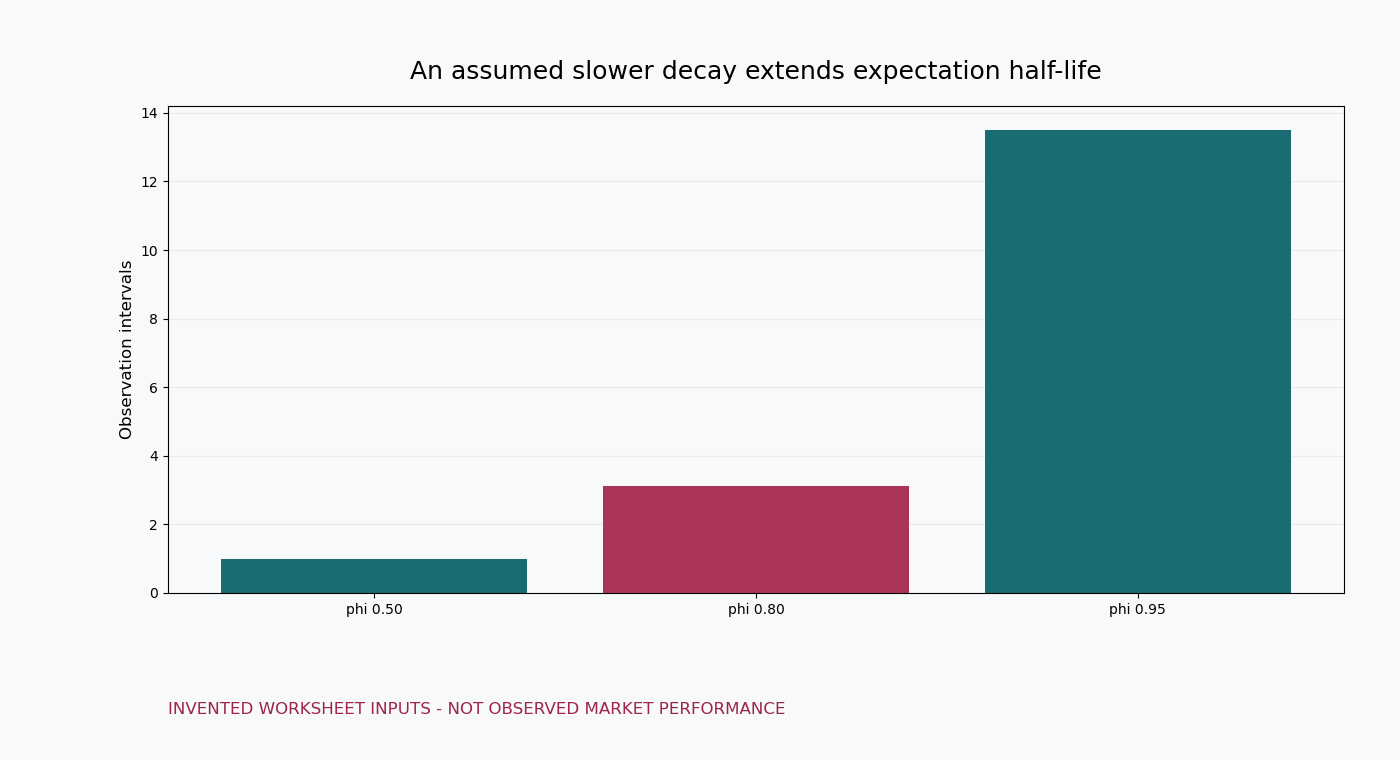
The price-series lab reports descriptive next-close behaviour. The decay worksheet translates an assumed positive AR(1) coefficient into an expectation half-life. The field guides explain why neither output establishes tradable fills, costs or stationarity. A valid rejection is useful: a claim that disappears under causal timing or plausible friction should not be made more persuasive with extra indicators.
Define a prior-window reference, measure absolute recovery and avoid calling every correctly directed move a successful reversion.
Understand positive AR(1) decay, observation clocks, coefficient sensitivity and why half-life is not a trade deadline.
Design a bounded stationarity experiment without turning a unit-root test, fitted spread or chosen chart into proof of trading profit.
Define what returning toward a mean actually measures before treating a directional move as recovery or a statistical pattern as a trade.
Define the unchanged reference, eligible deviation and later distance before calling a price move recovery. Statistical behavior and trade economics remain separate.
The expanded workbook follows seven authored paths from an initial observation through a declared horizon. Its default improves, reaches a band and touches the reference, then ends away from it. Another crosses the reference immediately but moves farther away. A third alternates at equal distance and never becomes strictly closer. Complete JSON and a ledger retain all declared values, including unused later observations. These are fictional EDU prices, not a market backtest. They make the outcome rule inspectable before a reader calls a visually plausible reversal a trading edge.
A prior-price mean, a fitted two-leg spread equilibrium and a changed destination need different evidence. The three filled cards describe those contracts without pretending their real sources or independent masters exist. The original causal price lab, conditional AR(1) worksheet and reference workbench remain available. Twelve new guides trace endpoints, observation clocks, event overlap, scale, process choice, structural changes, selection and native execution. A local path lens supplements those tools with exact decimal distance arithmetic. None trains a model, estimates a real win probability or promotes a strategy to production.